Types of investments: how does each one make money?
Stocks, bonds, funds, gold… The names are familiar, but how they make money is not always clear. Some investments generate regular income, while others depend on gaining value over time.
In Brief
- An investment pays off either through regular income (interest, dividends, rent) or through a rise in value.
- Higher return potential comes with higher risk; stocks are more volatile than bonds.
- Funds let you own a slice of many assets at once without picking each one.
Stocks and bonds: owning or lending
Buying a stock means owning a small piece of a company. A share bought at $100 and sold at $120 earns $20 before fees and taxes. Some companies pay dividends, but this is not required and can be cut.
A stock’s price depends not only on today’s profits but also on the economy, competition and future expectations. If the company goes bankrupt, the whole investment can be lost.
With a bond, you lend money to a company or government. A $1,000, 5-year bond paying 5% pays $50 a year and returns the principal at maturity. If market rates rise, older bonds lose value; selling before maturity can mean a loss.
Funds: a bit of everything
A fund is like an assorted bread basket. One share gives a small slice of everything the fund owns.
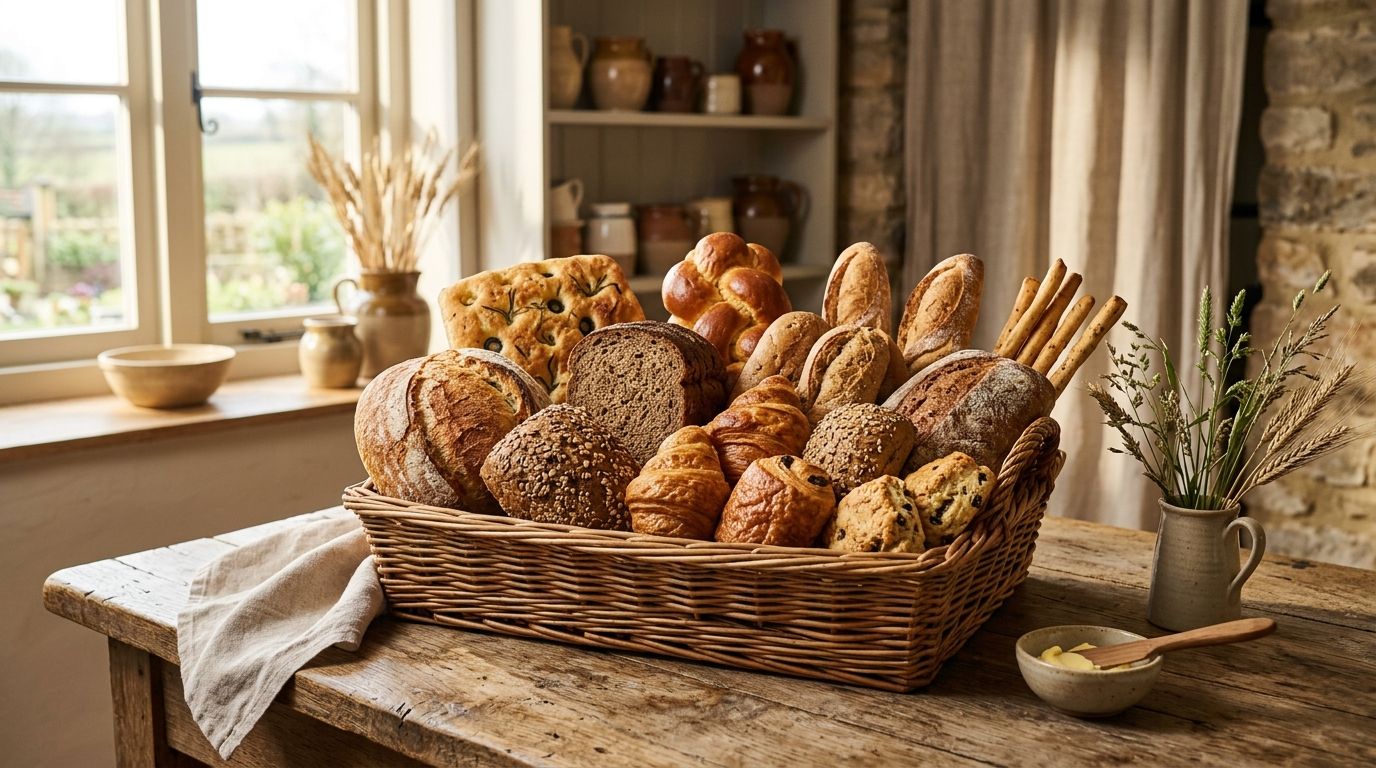
- Mutual funds: A manager makes the picks. Active management usually means higher fees, and the price is set once a day, after the close.
- Index funds: Track an index such as the S&P 500. They need little management, so fees are usually low.
- Exchange-traded funds (ETFs): Trade during the day like a stock. They can track an index or be actively managed.
Even small fee differences can noticeably affect returns over the long run.
Real estate and commodities: tangible assets
A home offers rental income and potential appreciation. But maintenance, taxes, insurance and mortgage payments eat into rent; a property can sit empty for months and is hard to sell quickly.
Real estate investment trusts (REITs) let you share in rental income without buying a building, and they trade easily on an exchange.
The prices of commodities such as gold, silver, oil and agricultural products depend on supply and demand. Because they do not always move with stocks and bonds, they help with diversification. But they pay no interest or dividends, and futures contracts carry serious risk.
Cash and the rest
Savings accounts, certificates of deposit, money market funds and short-term Treasury bills are low risk. Unlike insured bank deposits, money market funds can lose value. If cash-like assets fall behind inflation, purchasing power erodes.
In private equity funds, which invest in companies that are not publicly traded, money can stay locked up for years. With collectibles such as art or rare watches, profit depends on finding a buyer willing to pay more.
Key Assets
| Asset | Outlook | Why? | Key Level |
|---|---|---|---|
| Stocks | Watching | High long-term return, high volatility | Company debt and profits |
| Bonds | Neutral | Predictable interest, sensitive to rate hikes | Market interest rate |
| Index funds and ETFs | Neutral | Broad diversification at low cost | Annual expense ratio |
| Real estate | Watching | Rental income, low liquidity | Rent after costs |
| Commodities | Watching | Inflation balance, no income | Supply-demand balance |
| Cash equivalents | Neutral | Low risk, inflation risk | Inflation rate |
What to Watch
- Diversification lowers risk but does not remove the chance of loss.
- Instruments that are not well understood, especially futures and collectibles, can lead to unexpected losses.
- The right mix depends on goals, time horizon and the level of risk that can be carried.
This note was compiled from open-source data and content available online; it does not constitute investment advice.
This article is for general information only and is not investment advice.